Your Israeli pension, explained in English
For olim and hi-tech employees: pension funds, keren hishtalmut, provident funds and insurance, reviewed and managed by one licensed agent who speaks your language.
- Licensed by the Capital Market Authority
- Free first review, no obligation
- English, עברית, Русский
Free pension review in English
Most savers in Israel don't know what their pension costs them, or where their money is invested.
One structured review through the national pension clearinghouse (Mislaka) and the insurance registry (Har HaBituach) shows the whole picture: every fund, policy and provider.
What we check
- Management feesOn deposits and on savings, in every fund
- Investment tracksWhether your track fits your age and goals
- Insurance coverSurvivors and disability cover: gaps or double cover
- Forgotten fundsOld accounts from past jobs that still charge fees
- Employer depositsWhether deposits arrive on time and at the right rate
Free pension check
Leave your details and Moshe will call you back today on business days.
Loading form…
Or talk to us now:
Built for how you work in Israel
Hi-tech salaries, job changes every few years, and a pension system that runs in Hebrew.
Hi-tech employees
Check employer deposits, fees and investment tracks after every job change.
Pension for hi-tech
Olim from the US, UK, Canada and beyond
How Israeli pensions and keren hishtalmut work, in plain English.
Pension guide for olim
Young families
Savings for the kids, life insurance and a plan for the first apartment.
Family savings
Pension for hi-tech employees in Israel
High salaries, stock grants and frequent job changes make hi-tech pensions more complex than they look on the payslip.
- Salary above the comprehensive pension fund ceiling: deposits on the part above it go to a general fund or manager's insurance, with different fees and cover
- Keren hishtalmut above the tax-free salary ceiling: deposits above it are taxable, so it's worth knowing how it affects your payslip
- Fees after a job change: group discounts often end when you leave, and fees on the old fund can rise
- Disability cover sized to a high salary, not just the default in the fund
- RSUs and options (section 102) are not part of your pension, so we look at the full picture and coordinate tax questions with your accountant
Pension help for olim, in English
Olim and returning residents often arrive with savings abroad and no idea what their Israeli payslip deductions mean. We explain everything in plain English.
- What every line of your payslip means: pension, severance, keren hishtalmut
- Whether your employer's deposits arrive on time and at the right rate
- Choosing the right pension fund and investment track for you
- Coordinating with your accountant on pensions and savings from abroad
What we do
Everything about your long-term savings and family protection – with one agent who knows you.
Free pension check
We review fees, investment tracks, insurance cover and forgotten inactive funds across all providers.
Retirement planning
When to retire, how to withdraw, tax exemptions (Form 161D) and severance – a plan for the years before and after.
Transfer & merge funds
Several pension funds from past jobs? We merge them the right way – without losing seniority or cover.
Lower management fees
Half a percent can be worth tens of thousands of shekels by retirement. We negotiate and compare.
Self-employed (Atzmai) pension
Mandatory deposits, tax benefits, Keren Hishtalmut for the self-employed and disability cover.
Keren Hishtalmut & Kupat Gemel
Choose the right track, lower fees and plan the tax-free withdrawal.
Bituach Menahalim vs. pension fund
Clear comparison of fees, conversion factors and cover – before you change anything.
Life, health & disability insurance
We check the national insurance database (Har HaBituach), remove duplicates and add only what's missing.
How it works
Three simple steps – we do most of the work for you.
Intro call
20 minutes by phone, Zoom or at our office. We learn your situation and goals.
Full review
With your consent we pull all your data from the national pension clearinghouse (Mislaka) and analyze it.
Plan & follow-up
You get clear recommendations in numbers; we handle the paperwork and keep checking over the years.
Pension & fee calculators
Play with the numbers – then we'll calculate from your real data.
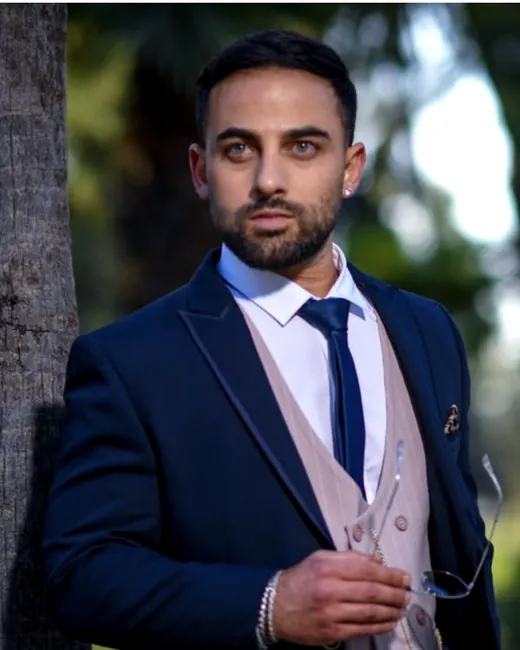
Meet Moshe Ifrach
Moshe Ifrach is a licensed pension insurance agent at Derech Eretz Pension Insurance Agency. He guides employees, hi-tech professionals, the self-employed and families through every pension decision, from the first payslip to retirement.
Derech Eretz was founded in 2012. Our approach is simple: check thoroughly, explain clearly, recommend only what fits you, and stay available long after you sign.
Frequently asked questions
Do you work with English speakers?
Yes. Meetings, explanations and follow-up can be in English. Official forms are in Hebrew – we walk you through every line.
What's the difference between a pension agent and a pension advisor?
Both are licensed by the Capital Market Authority. A pension advisor (yoetz) is independent and charges a fee; a pension insurance agent (sochen) markets pension products and is paid commissions by the providers he works with – and must disclose this to you. Our first review is free.
What is the Mislaka?
Israel's pension clearinghouse. With your signed consent, it lets us see all your pension savings across all providers in one place.
When can I withdraw my Keren Hishtalmut?
Usually after 6 years, with tax-free gains (some exceptions apply, e.g. studies after 3 years). You can also keep it invested.
I'm self-employed in Israel – must I deposit to a pension?
Yes. Since 2017 self-employed people must deposit to a pension fund at tiered rates of income, and deposits bring meaningful tax benefits.
Can everything be done remotely?
Yes – consent and documents are signed digitally and meetings can be by Zoom or phone. You're also welcome at our office in Rishon LeZion.
Is there an English-speaking pension agent in Israel?
Yes. Moshe Ifrach is a licensed pension insurance agent who works with olim and hi-tech employees in English.
I just changed jobs in hi-tech. What happens to my pension fund?
The fund stays yours. Your new employer can deposit into it or open another one. It's worth checking that the fees didn't rise after you left, and whether to merge old funds.
Can you help with US or UK pensions?
We focus on your Israeli pension, keren hishtalmut and insurance. For pensions abroad and cross-border tax, we coordinate with your accountant so the plan fits together.
Ready to check your pension?
A 20-minute call can change your family's financial future. Free, no obligation.